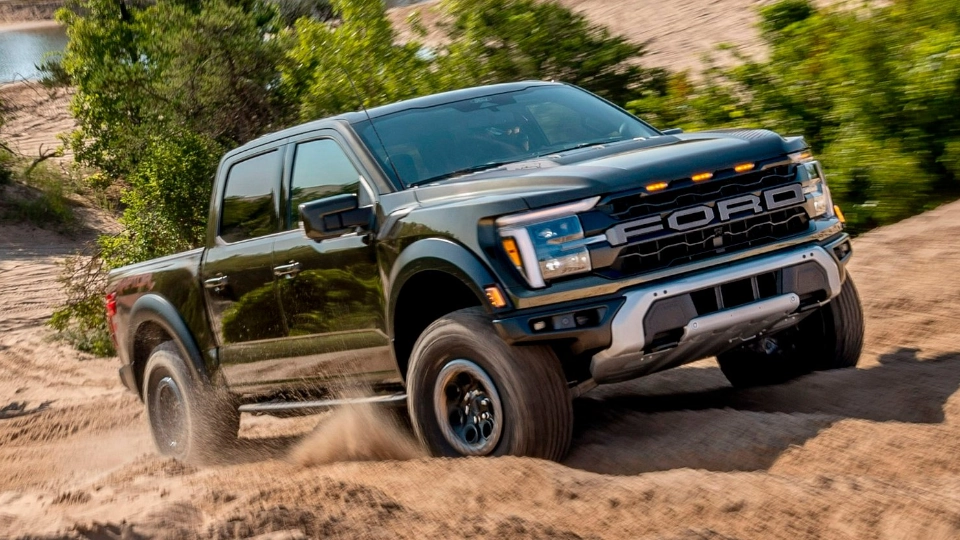
Ask a room of truck owners how to find the best deals on Ford F-150 and Ram trucks and most will give you a version of the same advice: haggle harder. The haggling matters, but it happens at the end of a longer game. A truck purchase is really four separate transactions wearing one set of paperwork — the selling price of the new truck, the manufacturer incentives attached to it, the value of your trade-in, and the loan that carries the balance. Dealers are happiest when those four blur together into a single monthly payment, because a blur is easy to tilt in their favor. Your job, before you ever sit down, is to pull them apart and settle each one on its own evidence.
Number one: the F-150 or Ram selling price, researched before it is negotiated
Start with homework, not handshakes. Both the F-150 and the Ram 1500 are built in dozens of configurations, and the same nameplate can span an enormous price range depending on cab, bed, engine, and trim. Decide which configuration actually does your work — towing, hauling, commuting, or some honest mix — because every unused capability is purchase price and fuel you bought for no reason. The federal fuel economy guide at FuelEconomy.gov lets you compare the exact engine and drivetrain combinations side by side, and on a vehicle you may keep for a decade, a couple of miles per gallon of difference quietly outweighs a loudly negotiated discount. While researching, read our parallel breakdown of Chevy Silverado features and deals — cross-shopping a third truck is the cheapest leverage you will ever own, because it turns “your best price” into a claim that has to beat somebody.
Number two: incentives, which change while the truck does not
Manufacturers sweeten these trucks in cycles — cash-back offers, subsidized financing, lease support, and targeted rebates for groups like recent graduates, military members, or owners of a competing brand. The truck sitting on the lot is identical in March and in April; the incentive stack is not. Two practical consequences follow. First, ask every dealer to itemize which incentives are in their quote, because a low number built on rebates you do not qualify for is not a low number. Second, leftover previous-model-year trucks are where incentives concentrate: when the new model year arrives, the factory helps dealers clear the old one, and a truck that differs from its replacement mostly in badging gets priced like a secret. Patience is a negotiating position. If your current vehicle runs, the calendar works for you and against the lot.
Number three: your trade-in is a separate sale
The oldest trick in the business is a generous trade-in allowance quietly recovered through a firmer price on the new truck — the total is what matters, and the total is what gets hidden. Break the link. Get your current vehicle appraised or offered on by at least one buyer who is not selling you the replacement, so you walk in knowing its standalone value. Then negotiate the new truck’s price first, completely, before the trade enters the conversation. If the dealer’s eventual trade figure matches your outside benchmark, combining them costs you nothing. If it does not, you can sell separately with a clear conscience. The same discipline applies at the budget end of the market, as our guide to used cars for just a few thousand dollars shows: every number gets its own evidence, or it gets doubted.
Number four: financing, where quiet money moves
A point of interest across a long truck loan can cost more than the discount you celebrated. The Consumer Financial Protection Bureau’s auto loan tools make the essential point plainly: shop for the loan the way you shopped for the truck. Get a pre-approval from your own bank or credit union before visiting the dealer, then let the dealer try to beat it — dealer-arranged financing is sometimes genuinely competitive, but only when it has to compete. Watch the loan term as carefully as the rate, because stretching a loan to shrink the payment usually inflates the total interest and can leave you owing more than a depreciating truck is worth. And read the safety file while you are at it: the Insurance Institute for Highway Safety’s ratings for the 2025 Ford F-150 crew cab show how cab configuration changes crash performance, one more reason the exact build deserves more attention than the badge.
Putting the four numbers on one page
Before signing anything, ask for the complete deal written as four lines: agreed price of the truck, itemized incentives, trade-in value, and the loan’s rate, term, and total interest. If a line cannot be shown, it is being hidden inside another one. This one-page habit transfers beyond trucks — it is the same thinking behind buying used equipment well, as in our look at repossessed tractor opportunities, where separating the machine’s price from the auction fees and financing is the whole skill. Dealers handle thousands of these transactions; you handle one every several years. The page is how you close that experience gap.
The bottom line
Learning how to find the best deals on Ford F-150 and Ram trucks is less about toughness than about structure. Research the exact configuration and its fuel costs, let incentives and leftover model years do their seasonal work, price your trade-in as its own transaction, and force the financing to compete for you. Settle each of the four numbers on its own evidence and the fifth number — the total — takes care of itself.